Chicago & Cook County cost segregation
Bigger depreciation deductions, sooner, on your two-flat, greystone, condo or small commercial building. Studies from $495, usually delivered the next business day.
Operated by Cost Seg Smart. Free estimate takes about a minute, no sign-up.
How it works
Enter your purchase price and property type to see a likely Year-1 deduction range. It takes about a minute.
Share your closing statement and a few property details. Most residential studies are done remotely, with no walkthrough to schedule.
You receive a report with the component schedule, depreciation tables and methodology, ready for your tax return.
Built for Chicago's building stock
Get a free estimate in about a minute, then decide. Studies start at $495.
Chicago by the numbers
We ran 5 typical Chicago-area properties through the same engine that produces our studies. These are engine estimates, not promises about any one property.
Results vary with actual property condition, year built, renovation history, county assessor data and rental treatment (STR vs LTR). Each property was run with industry-standard 2026 base costs, the BLS PPI time index, county assessor land allocation, IRS Pub. 946 / Rev. Proc. 87-56 MACRS classification and 100% bonus depreciation per OBBBA. Full per-property table and downloadable CSV/PDF on the Chicago cost seg benchmarks page.
| Purchase price | $685,000 |
| Depreciable basis | $510,325 |
| Land allocation | 25.5% |
| 5-year reclassified | $31,234 |
| 15-year reclassified | $49,983 |
| Total reclass | 15.9% |
| Purchase price | $545,000 |
| Depreciable basis | $408,750 |
| Land allocation | 25.0% |
| 5-year reclassified | $24,443 |
| 15-year reclassified | $23,859 |
| Total reclass | 11.8% |
| Purchase price | $425,000 |
| Depreciable basis | $318,750 |
| Land allocation | 25.0% |
| 5-year reclassified | $22,776 |
| 15-year reclassified | $17,547 |
| Total reclass | 12.7% |
| Purchase price | $685,000 |
| Depreciable basis | $513,750 |
| Land allocation | 25.0% |
| 5-year reclassified | $71,594 |
| 15-year reclassified | $4,419 |
| Total reclass | 14.8% |
| Purchase price | $485,000 |
| Depreciable basis | $378,300 |
| Land allocation | 22.0% |
| 5-year reclassified | $20,174 |
| 15-year reclassified | $30,773 |
| Total reclass | 13.5% |
Neighborhoods we serve
Cost segregation results vary more by neighborhood than by city. Here is how the main Chicago sub-markets typically compare.
Typical value $685,000Typical land ~30%
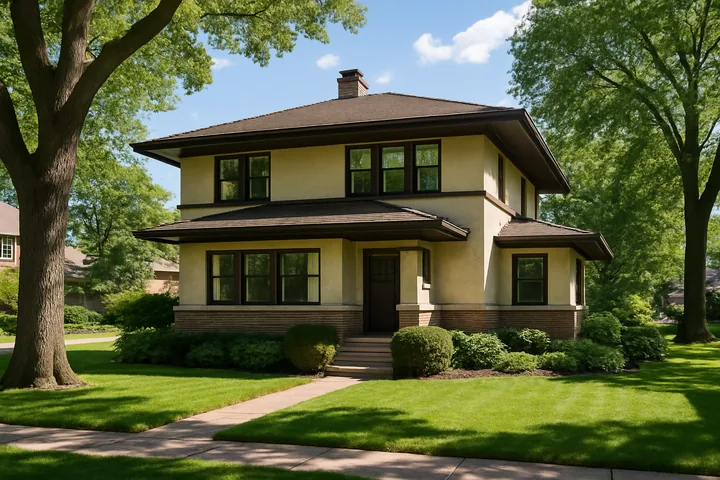
Pre-war 1890s–1920s SFR and two-flat stock heavily renovated. Higher land allocation due to neighborhood-scarcity premium. Mix of fix-and-flip and small-MF investor activity.
Typical value $545,000Typical land ~26%
Two-flat, three-flat, and small-multifamily dominant. Mid-tier land allocation. Active small-MF investor market with heavy post-2010 renovation activity.
Typical value $425,000Typical land ~22%
1890s-1920s small-MF and SFR stock. Lower-cost entry point. Strong fix-and-flip and BRRRR activity. Lower land allocation.
Typical value $685,000Typical land ~32%
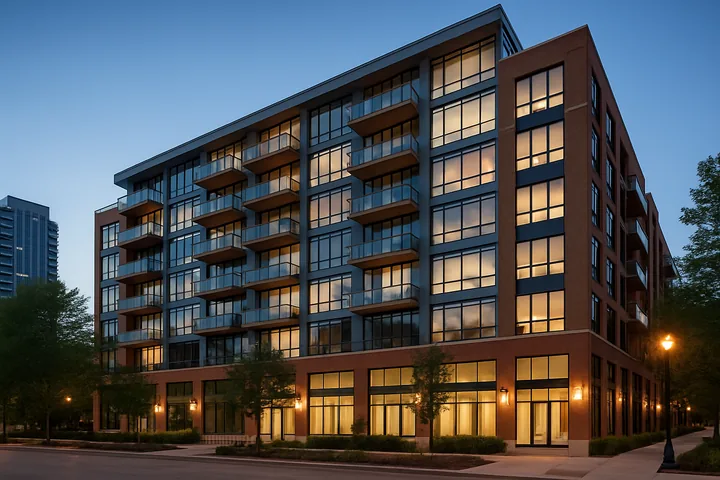
Post-2010 mid-rise and high-rise condo dominant. Higher land allocation reflecting downtown-adjacent premium. New construction with cleaner reclassification ratios.
Typical value $485,000Typical land ~24%
Suburban Cook County SFR rental market. Strong year-round LTR cash flow. Mid-tier land allocation. Outside Chicago STR ordinance jurisdiction.
Also serving investors in Lakeview, Uptown, Rogers Park, Edgewater, Ravenswood, Humboldt Park, Albany Park, Irving Park, Portage Park, Bronzeville, Hyde Park, Little Village, Berwyn, Cicero, Skokie, and the rest of Cook County.
Methodology note: "Typical land" reflects baseline patterns for the sub-market. Where reconstruction cost exceeds 2.0× the implied depreciable basis after subtracting baseline land, the engine applies a premium land floor (~50%), so an individual property can run above the neighborhood typical. See the Chicago data page for per-property land-source attribution.
Know before you buy
Chicago's cost-seg picture has two layers: a clean federal-acceleration story under OBBBA's restored 100% bonus depreciation, and a more complex Illinois state-side picture that's frequently misrepresented elsewhere. Illinois is not fully conforming on federal §168(k). The Illinois Income Tax Act (35 ILCS 5/203) requires addition modifications for federal bonus depreciation with subsequent subtraction modifications that recover the deduction across multiple Illinois tax years, your federal Year-1 cash captures cleanly, but the Illinois-side benefit is spread rather than fully accelerated. A Chicago investor taking $80,000 of accelerated reclassification at the 37% federal bracket captures $29,600 of Year-1 federal cash, with the Illinois-side $3,960 total benefit spread over multiple state tax years rather than concentrated in Year 1. The federal benefit is real; the Illinois timing math is more complex than a simple flat-rate calculation suggests.
The bigger practical constraint on Chicago cost-seg is the regulatory STR environment. Chicago's Shared Housing Ordinance restricts short-term rental operations to registered hosts with significant compliance requirements, limits on density, and restrictions on whole-unit non-primary-residence STR. Most cost-seg-relevant Chicago property operates as long-term rental, pre-war SFR fix-and-flip in Lincoln Park, Bucktown, and Wicker Park; two-flat and three-flat small-multifamily acquisitions in Logan Square, Avondale, and Pilsen; downtown-adjacent condo rental in South Loop and West Loop; and suburban Cook County SFR rental in Oak Park and Evanston (outside Chicago city jurisdiction).
Chicago two-flats and three-flats are common cost-seg candidates. The 1890s–1920s small-multifamily stock in Logan Square, Avondale, Pilsen, and Bridgeport typically features multiple FF&E packages per building (each unit has its own kitchen, bathrooms, appliances), shared-system depreciation considerations (boiler, electrical service, structural masonry), and substantial post-2000 renovation cost pools. Our published reclassification bands are 8–21% for a two-flat (duplex) and 8–26% for a three-flat (triplex); well-documented post-2010 renovation is what moves a study toward the top of its band, and individual results vary with renovation history and property condition.
Decoupling: Illinois has historically required IL Schedule M addition modifications for federal bonus depreciation, with corresponding subtraction modifications recovering the deduction over future Illinois tax years. Model federal and Illinois treatment separately, they do not match year-by-year even when the total deduction is equivalent over the property's holding period.
Verify with your CPA. State conformity rules for federal §168(k) bonus depreciation change often. This page reflects our understanding as of May 2026; confirm current-year treatment with a qualified CPA or tax attorney before relying on specific dollar projections.
Chicago Shared Housing Ordinance restricts short-term rental operations within City of Chicago limits, STR registration is required, density caps apply in certain residential zones, and whole-unit non-primary-residence STR operation is largely prohibited. Suburban Cook County, DuPage County, Lake County, and Will County operate distinct regulatory regimes, some more permissive than Chicago proper. For STR-intent buyers, jurisdictional verification matters more than the cost-seg study itself. For LTR investors (the dominant cost-seg-relevant Chicago segment), standard §469 passive-loss rules apply, and real-estate-professional status under §469(c)(7) is the typical path for high-volume operators wanting W-2 offset. The federal §168(k) acceleration captures Year-1 cleanly; the Illinois state-side benefit is spread across multiple tax years per IITA modification rules rather than concentrated in Year 1, model both treatments separately in your CPA workflow.
For the full IRS-rule reference layer (§168(k), §469 material participation, state conformity), see irsdepreciationrules.com, our open reference site.
Questions
No, and this is one of the most commonly misrepresented points about Illinois state tax treatment. While Illinois starts state taxable income from federal taxable income and applies the flat 4.95% rate, the Illinois Income Tax Act (35 ILCS 5/203) requires addition modifications for federal bonus depreciation with subsequent subtraction modifications. The practical effect: your federal §168(k) acceleration under OBBBA's 100% bonus captures cleanly in Year 1 on the federal return, but Illinois requires the state-side acceleration to be spread across multiple Illinois tax years rather than concentrated in Year 1. The total Illinois benefit over the property's holding period equals what full conformity would produce, but the timing differs. Verify current-year Illinois treatment with your CPA, IL bonus depreciation rules have been adjusted multiple times in recent years. This makes Illinois materially less attractive than fully-conforming states (Colorado 4.40%, Utah 4.65%) for Year-1 cash, though the total federal-plus-state benefit over the hold period is similar.
Generally not in Chicago city limits in any way that supports the typical absentee §469 STR-loophole strategy. Chicago's Shared Housing Ordinance requires STR registration, restricts non-primary-residence absentee whole-unit STR operation, and imposes density caps in many residential zones. Adjacent suburban Cook County jurisdictions (Oak Park, Evanston, Skokie) and DuPage County (Naperville, Wheaton, Downers Grove) operate distinct STR regimes, some more permissive. For Chicago-resident investors specifically wanting §469 STR-loophole treatment, the practical path is to acquire property in adjacent permissive jurisdictions or pivot strategy to LTR + real-estate-professional status.
Each unit has its own kitchen, bath and appliance set, and those finishes and appliances are 5-year property; fencing, paving and landscaping are 15-year. The masonry shell, roof, boiler and central electrical service stay in the 27.5-year building. Our published reclassification band for a two-flat (duplex) is 8–21% of depreciable basis, typically 15%; a three-flat (triplex) is 8–26%, typically 17%. Where a building lands depends mostly on its finishes (carpet and vinyl reclassify, hardwood does not) and on documented renovation cost.
Neither reliably wins on reclass-as-percent-of-purchase. Our published bands for pre-war Chicago two-flats and three-flats in Logan Square, Avondale, Pilsen, and Bridgeport are 8–21% (two-flat) and 8–26% (three-flat); the multi-unit FF&E + renovation pool dynamic described above is what moves a building toward the top of its band. Downtown South Loop and West Loop condos carry higher land allocation (32%) reflecting the downtown-adjacent premium. Absolute dollar deductions are larger on the small-multifamily because basis is larger per total transaction ($425K–$685K for two-flat/three-flat vs $485K–$685K for single condo). For BRRRR portfolio operators, small-multifamily is the typical optimal target.
Not directly, the ordinance applies to STR operations, not long-term rental. LTR investors in Chicago operate under standard §469 passive-loss rules. The §469 STR-loophole that converts passive losses to active deductions doesn't apply to LTR property anywhere, so Chicago's STR restriction doesn't change the LTR cost-seg math. What matters for LTR investors is whether they can use cost-seg passive losses against passive rental income from other holdings, or whether they qualify as real-estate professionals under §469(c)(7) to convert losses to active W-2 offset. For high-volume Chicago BRRRR operators with 5+ properties, real-estate-professional status is typically achievable.
Usually not. Most residential studies, including two-flats, three-flats and condos, are prepared remotely from your closing documents, property records and photos, so there is no walkthrough to schedule. If an in-person site visit makes sense for your property, it is priced as its own line and you see it before you order.
Land cannot be depreciated, so every study sets it aside first. For Cook County properties the Cook County Assessor's split between land value and building value is a common starting point, and your report states which source the land figure came from. The Assessor reassesses one-third of the county each year, so City of Chicago values are refreshed on a three-year cycle.
Usually the next business day after you order and upload your documents. The study is delivered online as a CPA-ready PDF with the component schedule, depreciation tables and methodology.
More general cost-seg questions answered at costsegsmart.com/faq/. Comparing firms? See our Chicago provider comparison.
Free estimate first. When you are ready, studies start at $495 with transparent pricing on the main site.